ina ABA
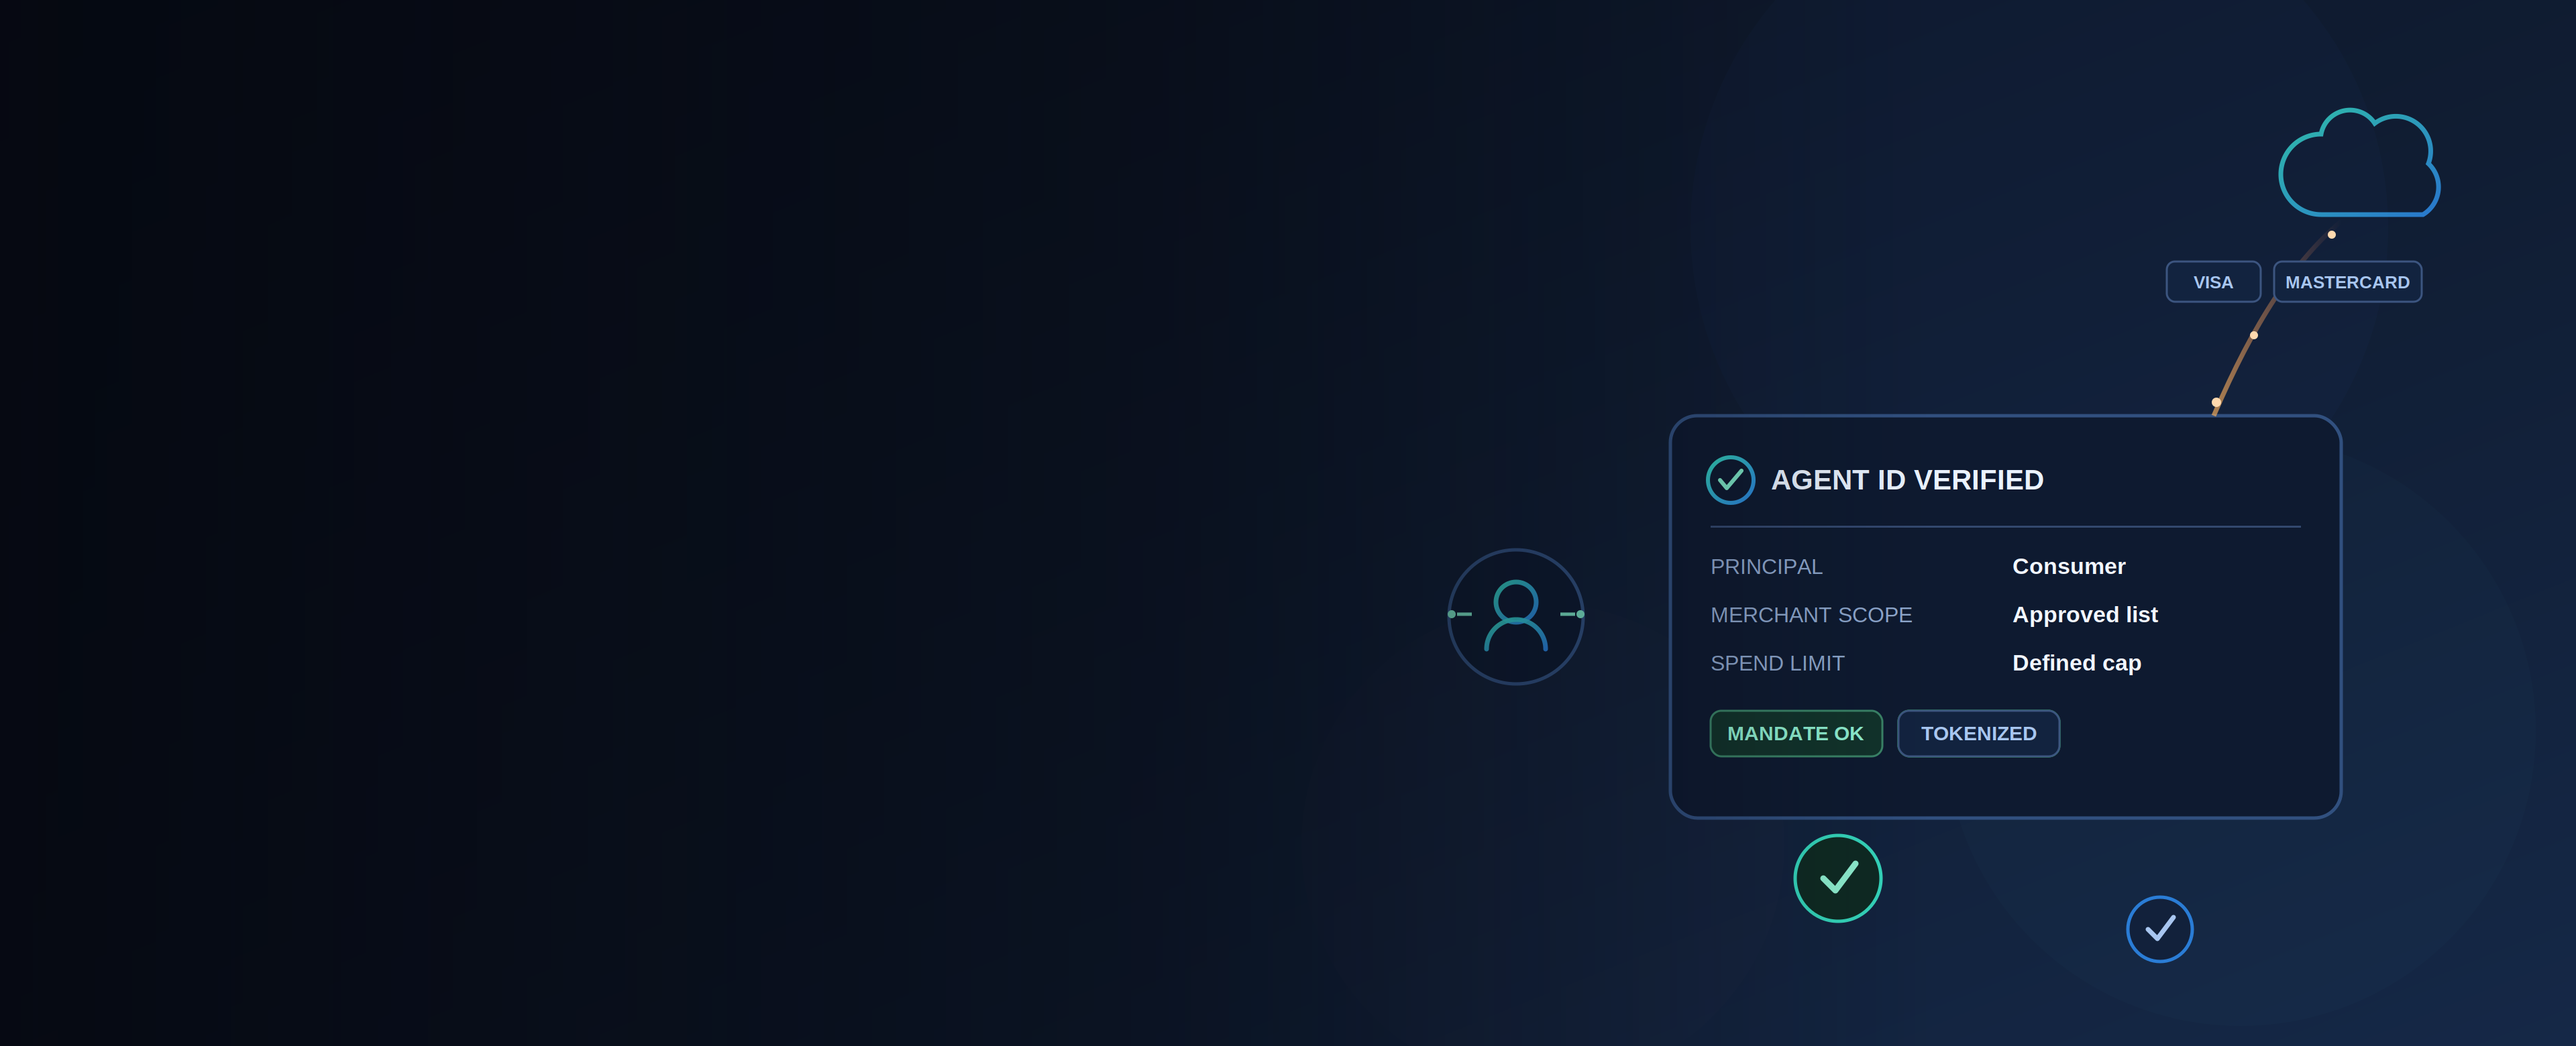
ina ABA is the orchestration layer for agentic eCommerce, where AI agents search, decide and pay on a customer's behalf. It verifies the agent, enforces what it is authorized to spend, and turns consumer intent into a machine-readable mandate.
Platform Architecture Overview
ina ABA sits between AI shopping agents and the merchants and networks they transact with. It verifies agent identity, confirms spending authority and enforces the mandate before a token or authorization reaches the network, abstracting network complexity while preserving each network's controls.
 Agent Gateway / Orchestration Server
 Mandate & Consent Server
 Token Vault Server
 Protocol Adapter Services
 Risk & Scoring Engine
 Reconciliation & Reporting Server
 Notification / Step-Up Server
Identity & Consent Layer
Token & Network Layer
Checkout & Risk Layer
Settlement & Evidence Layer
End-to-End Platform Architecture
From agent identity to settlement, one controlled transaction lifecycle
1. Agent Identity
A cryptographic agent identity, verified against a KYC'd agent developer registry, is mapped to a principal, merchant scope and spend policy.
2. Consent / Mandate
Consumer intent becomes a machine-readable mandate covering approved merchants, category, maximum transaction size, validity window and frequency policy.
3. Tokenization
Visa Token Service or Mastercard MDES issues and owns the token. ina's reference layer maps it to the agent, merchant and mandate without issuing or holding it.
4. Checkout Orchestration
One unified, merchant-facing API abstracts differences across every integrated rail so the merchant builds once.
5. Risk & Policy
Each transaction is scored against agent identity, principal, mandate, merchant, transaction and history, separately from the human fraud engine.
6. Authorization
Approve, step-up, decline or revoke outcomes are enforced in real time against the bound mandate.
7. Settlement
The transaction settles through the applicable network rail, like any other card transaction today.
8. Reconcile & Evidence
Agentic settlement data is tagged for reporting, while mandate and consent evidence is retained for dispute and liability resolution.
Core Technical Capabilities
Identity, mandate, token, risk and evidence controls for agentic commerce
Agent Identity Bound to a Principal
Every action traces to a registered, credentialed agent explicitly mapped to the principal, merchant scope and spend policy behind it.
Machine-Readable Mandates
Consumer intent, merchant scope, category, transaction limit, validity window and frequency become enforceable checkout policy.
Tokenization Without Reinventing the Network
Visa Token Service and Mastercard MDES retain token ownership while ina ABA maintains a lightweight reference mapping.
Risk Scored Separately From Human Fraud
Agent transactions receive a dedicated real-time score backed by approve, step-up, decline, revoke and granular kill-switch controls.
One Unified Merchant-Facing API
Merchants and PSPs integrate once while ina ABA absorbs protocol, token-model and dispute-process differences.
Evidence Built In From the Start
Every mandate, consent and authorization decision is captured to support dispute and liability resolution across network models.
Extended Capabilities
Advanced controls for secure agent-initiated transactions

Per-Agent Risk Scoring & Behavioral Baselines
Instant, Granular Kill Switch

Mandate Violation Detection

PCI-DSS Scoped Token Handling

Policy-Based Step-Up, No OTP Dependency

Normalized Dispute & Reconciliation Evidence
Who Integrates With the Platform
Agentic payment infrastructure for every participant in the transaction lifecycle
Merchants
Get one integration instead of many, structured risk controls and normalized reporting and revocation across agentic channels.
Payment Service Providers
Add agent-ready payment capabilities without replacing the PSP stack or rebuilding existing payment infrastructure.
Payment Gateways
Use the unified merchant-facing API so agent-initiated transactions flow through existing gateway infrastructure.
Card Networks and Schemes
Keep network-specific token issuance, controls and rules in place while ina ABA orchestrates above them.
AI Agent Developers
Register shopping, travel, procurement and personal assistant agents through a KYC'd registry and operate within a defined mandate.
Platform Facts
How ina ABA fits into the evolving agentic commerce ecosystem
Seven Coordinated Services
One agentic payment control plane spanning orchestration, consent, token references, adapters, risk, reconciliation and step-up.
Two Networks Actively Integrating
Visa and Mastercard integration is underway, with an architecture designed to extend to additional rails as standards mature.
Zero Token Ownership
ina ABA never issues or owns a network token; it maps and tracks tokens controlled by the network.
Not a PSP Replacement
The platform sits alongside existing PSP and gateway relationships as a strategic infrastructure layer.
Built for a Still-Forming Standard
The architecture adapts as agentic eCommerce standards and liability frameworks continue to mature.
FAQ
How does ina ABA determine whether an AI agent is authorized to complete a purchase?
Who carries the loss when an AI agent makes a purchase outside what it was authorized to do?
Does ina ABA issue or hold its own payment tokens?
How is fraud risk for AI agent transactions handled differently from normal card-not-present fraud?
Does adopting ina ABA mean replacing our existing PSP or payment gateway?
Partner With Us
Customer Trust Built on Global Reach and Consistent Reliability
0+
OEMs Partnered
0+
Countries
0+
PSPs Partnered